They Can Afford to Buy. Why Do Wealthy People Choose to Rent?
Some people own investment properties across several countries yet choose to rent the homes they live in. Why would someone with enough capital to buy prefer to remain a tenant? From Germany and Japan to Dubai and the Mediterranean, we explore the changing relationship between wealth, property and personal freedom.
Not long ago, owning a home was considered one of the clearest signs of a successful life. Education, career, family, mortgage — and finally, a property to call your own.
Today, that familiar sequence is no longer the only path.
Someone may have enough capital to purchase several apartments and still prefer to rent the home they live in. They might own investment properties in one country while renting a residence in another.
Why?
The answer goes beyond money. It reflects a changing understanding of freedom, security and what it actually means to feel at home.
The Home You Live In and the Property You Own
For someone with substantial capital, property as an investment and property as a place to live are two separate decisions.
An investment property is evaluated through returns, liquidity, risks, maintenance costs and market prospects.
A home is chosen differently: for its atmosphere, surroundings, climate, convenience and how well it suits a particular stage of life.
These priorities do not always align.
An apartment that generates excellent rental income may be located somewhere its owner has no desire to live.
And a beautiful villa that feels perfect for the next few years may not be the most sensible place to concentrate a significant portion of one's wealth.
This distinction has given rise to a strategy often called rentvesting: renting the home you live in while owning income-producing investments, including real estate.
It is not a rejection of ownership.
It is a separation of two purposes: building wealth and enjoying life.
When €700,000 Remains Available
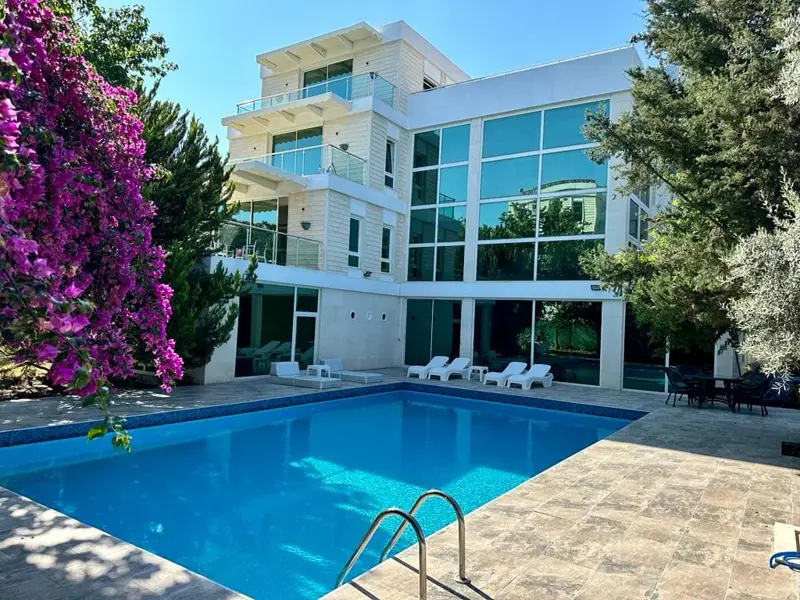
Imagine an entrepreneur considering a villa priced at €700,000.
They could purchase it outright. Alternatively, they could rent a comparable property for €3,000 per month and retain the capital for other investments.
The annual rent would be €36,000.
Over ten years, assuming the rent remains unchanged, the total would reach €360,000.
Now consider the capital that was not used to purchase the villa.
At a hypothetical annual return of 5%, €700,000 could generate €35,000 before taxes, fees and potential losses.
The potential investment income is remarkably close to the annual rental cost.
But this comparison is not proof that renting is financially superior.
Investment returns are uncertain. Rent may increase. Property values may appreciate, and homeowners avoid paying rent while building equity in an asset.
Ownership also involves transaction costs, maintenance, insurance and taxation, which vary significantly between countries.
A financially informed decision therefore considers the full cost of ownership, alternative investment opportunities, liquidity, risk and the expected period of residence.
Sometimes buying wins.
Sometimes renting does.
The real advantage lies in having the freedom to choose.
Germany and Switzerland: Renting Without Feeling Temporary
In parts of Europe, renting has long been an established way of life.
Germany has one of the highest proportions of renters in the European Union. Renting is also a significant part of the Swiss housing market.
The reasons are complex: property prices, financing conditions, taxation, tenant protections and cultural expectations.
Yet one important distinction stands out.
Renting does not necessarily mean waiting for the opportunity to buy.
People may remain in the same apartment for decades, invest in furniture, create beautiful interiors and build a lasting connection with their neighbourhood.
Of course, tenant security depends on legislation and individual contracts. High rents and housing shortages remain serious concerns in many cities.
Nevertheless, the broader idea is worth considering.
A home can feel permanent even when it does not legally belong to you.
Japan: A Home for Each Stage of Life
Japan offers another perspective.
In major cities, housing decisions are closely connected to employment, public transport, family size and everyday routines.
A young professional may prefer a compact apartment near a railway station.
A growing family needs more space.
Later in life, priorities may shift towards tranquillity, nature or the ability to work from home.
Rather than trying to find one property that will suit every decade of life, some people choose to change their living environment as their circumstances evolve.
This does not mean that Japanese society has abandoned homeownership. Ownership remains an important part of its housing market.
The interesting idea is simpler.
Perhaps our lives should not always have to adapt to a property we purchased many years ago.
Sometimes the property should adapt to the life we are living now.
Dubai: Separating Lifestyle from Investment
Dubai offers a different example.
As an international business centre, it attracts entrepreneurs, professionals and residents whose careers and personal circumstances may involve frequent relocation.
For someone uncertain whether they will stay for three years or fifteen, renting can provide valuable flexibility.
They can move closer to work, explore different neighbourhoods, upgrade their living space or adjust their lifestyle without selling a property.
At the same time, purchasing real estate in Dubai may make sense as an investment, a source of rental income or part of a long-term residence strategy.
A person can therefore own an investment apartment while renting the home they actually occupy.
There is no contradiction.
Their financial strategy and personal lifestyle simply serve different purposes.
The Mediterranean: Live There Before You Buy
The value of renting becomes particularly clear when moving abroad.
Imagine a family planning a new life by the Mediterranean Sea.
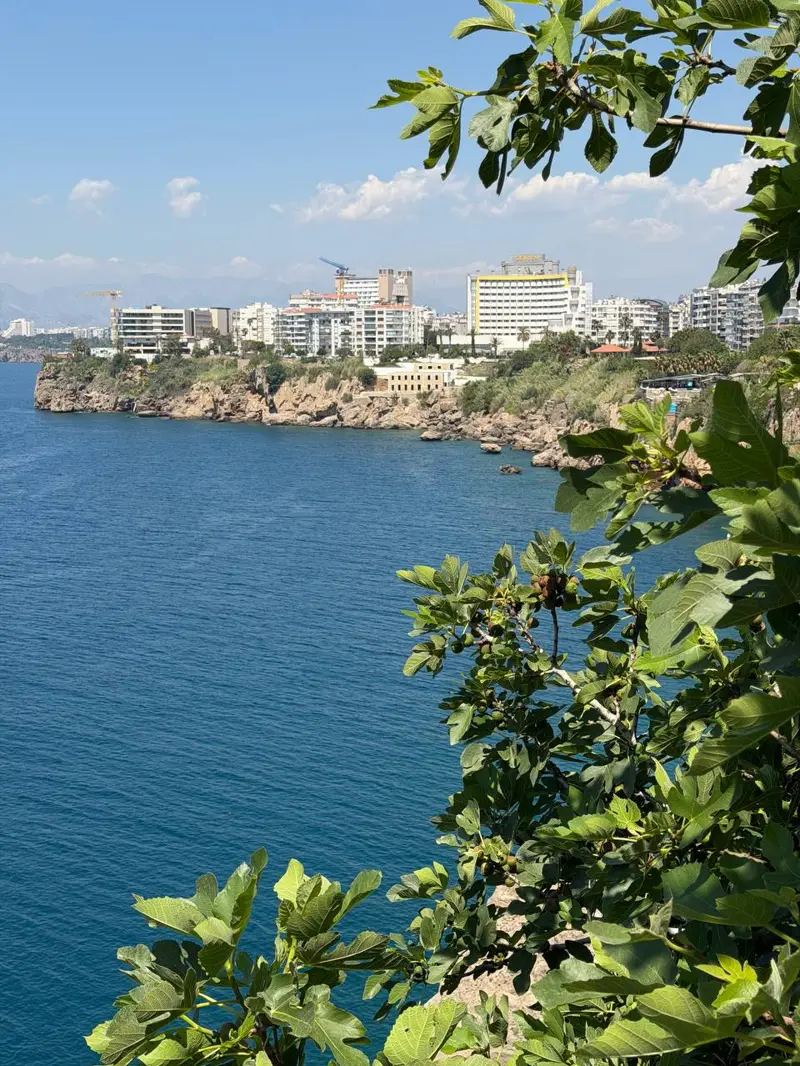
In photographs, Antalya, Fethiye and Bodrum may appear equally attractive: sunshine, terraces, greenery and beautiful coastlines.
But everyday life in these destinations can be remarkably different.
One neighbourhood may offer better access to schools and healthcare.
Another may be quieter during winter.
Some locations require a car for almost every journey.
Others become crowded during the summer tourist season.
A place that feels perfect during a two-week holiday may not be equally comfortable throughout the year.
Purchasing property before understanding a destination can turn an attractive assumption into an expensive commitment.
Renting for six or twelve months provides an opportunity to experience reality.
What is January like?
How busy does the area become in August?
How convenient is the airport?
Does the neighbourhood suit the children?
And most importantly, do you still want to live there once the holiday feeling disappears?
Such an experience may prevent a mistake far more expensive than a year of rent.
In Türkiye, foreign residents should also verify applicable residence, registration and rental requirements before making long-term plans.
After Sixty: When a Large House Becomes a Burden
There is another, less obvious reason to reconsider ownership.
A family home purchased decades earlier may gradually stop reflecting its owners' needs.
Children have moved out.
The garden requires constant maintenance.
Several rooms remain unused.
The costs continue, even though the lifestyle has changed.
For some people, selling a large property and moving into a rented apartment can simplify everyday life.
Instead of maintaining a large house, they may prefer a comfortable residence in a convenient neighbourhood, fewer responsibilities and greater financial flexibility.
But this approach is not suitable for everyone.
Later in life, stability, predictable expenses and security of tenure can become especially important.
Long-term renting should therefore be assessed not only for convenience but also for legal protection and financial resilience.
Why Renting Can Be Easier for the Wealthy
Here lies the central paradox.
For someone with substantial wealth, renting may represent freedom.
If the landlord decides to sell, they can find another home.
If the rent increases, they may have sufficient reserves.
If their circumstances change, they can relocate.
For a household with limited financial resources, those same events may create serious instability.
An unexpected move, rising rents or a shortage of suitable homes can turn flexibility into vulnerability.
Renting, therefore, does not automatically make someone freer.
Freedom comes not from the absence of ownership, but from having the resources and opportunities to choose.
That is the essential difference between renting out of necessity and renting as a deliberate lifestyle strategy.
But What If Buying Is the Better Choice?
Homeownership offers advantages that cannot be reduced to investment returns.
It allows people to personalise their surroundings, plan for the long term, reduce dependence on a landlord and, under appropriate circumstances, pass an asset to the next generation.
For many, owning a home represents emotional security.
It is where family memories are created, traditions develop and people imagine growing older.
Such value cannot be measured accurately through annual yields.
Yet the opposite situation also exists.
Someone may purchase property simply because ownership is socially expected, even when their career, family circumstances and ambitions call for mobility.
In that case, buying may become a limitation rather than an achievement.
There is no universal answer.
The important question is what someone is actually acquiring alongside the square metres: security, an investment, a particular lifestyle or a long-term obligation to remain in one place.
Perhaps Home Is Not Something We Own
Modern life is gradually changing our relationship with property.
Work is no longer always tied to an office.
Families live between countries.
Entrepreneurs manage businesses remotely.
People increasingly ask not only how much money they can earn, but also where and how they want to spend their time.
For some, owning a home remains an essential goal.
For others, the possibility of spending several years by the sea, moving to a major city and eventually choosing a quiet house surrounded by greenery is more appealing.
Neither choice makes someone more or less successful.
Perhaps the most important question is no longer:
“When are you going to buy your own home?”
But rather:
“If you had nothing to prove to anyone, where and how would you truly want to live?”
And there is another question — this time about money.
If you had one million euros, would you necessarily need to turn a substantial part of it into the walls around you?
Or is true luxury the ability to choose?
INEST HOMES explores real estate not only as ownership and investment, but as a setting for life. Sometimes buying is the right decision. Sometimes renting first makes more sense. What matters is that the choice reflects your own plans rather than someone else's expectations.